Bandhan Bank Launches Sparks, Ignite, Flare and Lumina: Its First Real Credit Card Portfolio
Last updated on
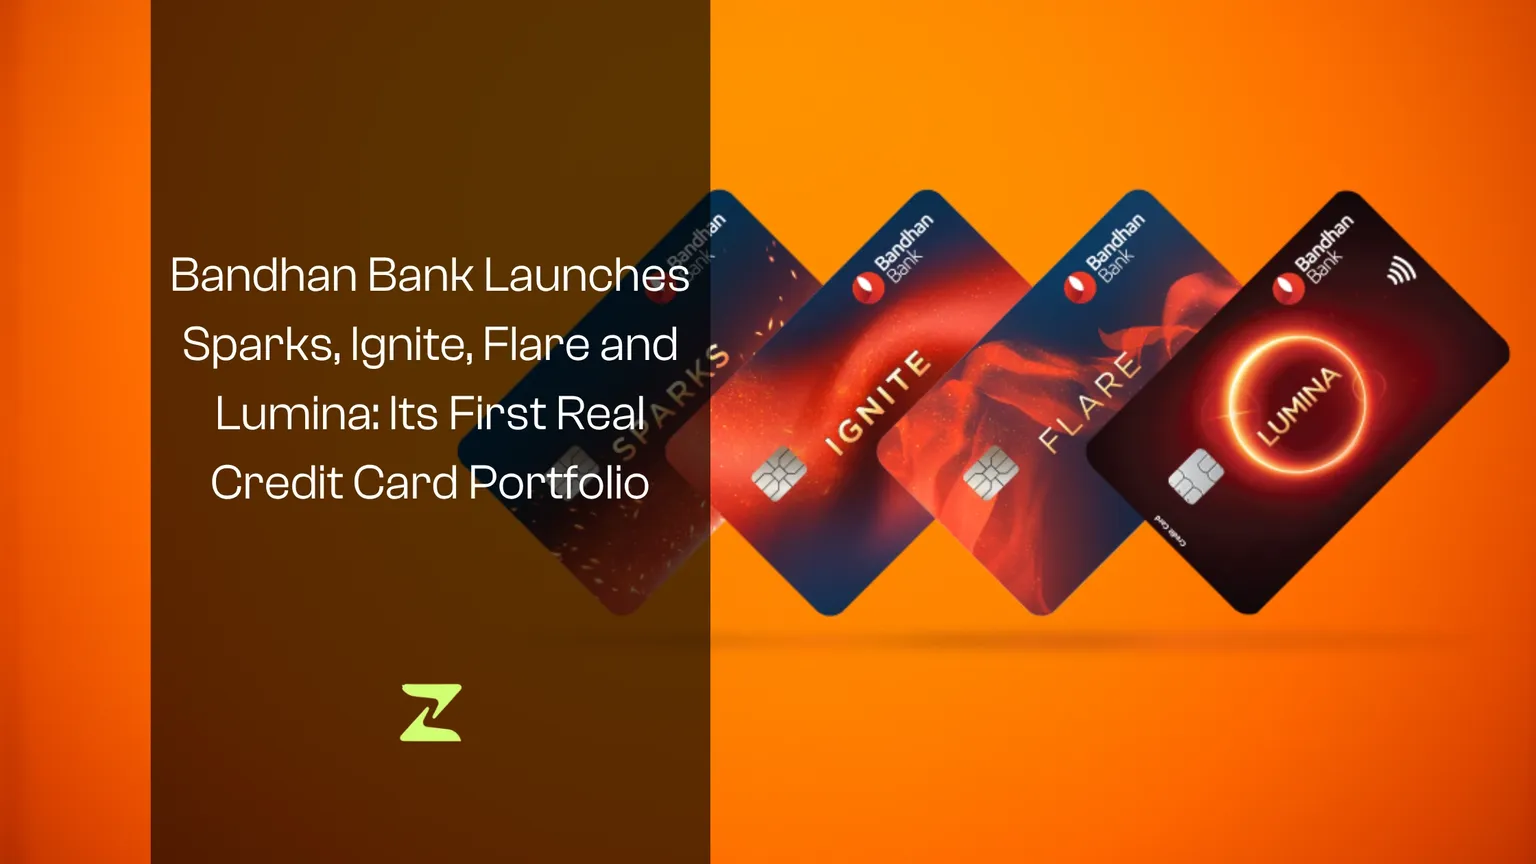
Bandhan Bank launched four Mastercard credit cards on 7 September 2026. We checked the fees, reward rates, and interest terms, including a rate gap that most coverage missed.
Too busy to read endless reviews & research?
Find the best cards that suit your lifestyle in 30 seconds
Try Monzy NowNo signup or email required
Bandhan Bank has launched its first credit card portfolio issued directly by the bank, in partnership with Mastercard. This move marks a new phase in the bank’s retail banking strategy, bringing varied credit card offerings with different spending needs and preferences.
The four cards – Sparks, Ignite, Flare and Lumina – cater to distinct customer segments, with benefits spanning rewards, lifestyle, travel and everyday spending.
The launch strengthens Bandhan’s retail product offerings as it seeks to deepen relationships with existing customers while reaching new ones.
The four cards, side by side
Bandhan Bank is pitching the cards at different kinds of spenders, including GenZ starting out, frequent travellers, and people who want the premium extras.
We pulled every detail to help you understand what’s on offer.
Sparks | Ignite | Flare | Lumina | |
|---|---|---|---|---|
Joining fee | Nil | Nil | ₹2,499 + GST | ₹9,999 + GST |
Renewal fee | ₹499 + GST | ₹999 + GST | ₹2,499 + GST | ₹9,999 + GST |
Fee waived if | ₹50K annual spend | ₹1L annual spend | ₹6L annual spend | ₹12L annual spend |
Reward rate | 2 points per ₹200 | 4 points per ₹200 | 10 points per ₹200 | 16 points per ₹200 |
Bonus rate | Extra points on ₹20,000+ monthly grocery & apparel spends | 8 points on grocery & travel | Extra points on ₹25,000+ monthly travel spends | 24 points on international spends |
Forex markup | 3.50% | 3.50% | 1.99% | 1.00% |
Lounge access (per quarter) | 1 domestic | 1 domestic, 1 international | 4 domestic, 1 international | 8 domestic, unlimited international |
Welcome benefit | 500 points on ₹5,000 spend in the first 30 days | – | ₹2,000 Amazon Pay voucher on ₹10,000 spend in the first 30 days | ₹10,000 Oberoi Hotels e-voucher, on ₹20,000 spend in the first 30 days |
The catch: different interest rates
It’s easy to miss, as it's only in the fine print. On Flare and Lumina, the interest rate you pay on any unpaid balance depends on whether you already have an account with Bandhan.
On Flare, the interest rate is 2.00% a month if you already bank with them, and 3.50% a month if you don't. On Lumina, it's 1.50% versus 3.50%. On Sparks and Ignite, it’s 3.50% for everyone.
So, if you're applying for Flare or Lumina without an existing Bandhan account, you're on the higher rate. However, this only matters if you carry a balance instead of paying your bill in full. If you pay in full, the interest rate never touches you.
One more thing worth knowing: Bandhan's pages also show a "Value Chart," adding every possible perk into one big annual number next to the fee. Sparks card claims ₹10,000 a year in benefits against a ₹499 fee, Lumina claims ₹1,78,900 against ₹9,999, and so on. Just treat it as rewards ceilings, not standard benefits.
Should you apply?
If you already bank with Bandhan, Sparks or Ignite are reasonable low-commitment cards to add. Flare or Lumina make sense too. The lounge access and reward rates are competitive with other issuers. But we know nothing about how smooth claims, redemptions or customer service are.
If you spend abroad, Lumina's 1.00% and Flare's 1.99% forex markup are the two worth checking out. Whichever card you pick, choose local currency at the terminal, because paying in rupees can cost you more than the markup.
IDFC FIRST cut its forex markup to zero on all its cards two days after this launch, though most of them stop earning points on foreign spends from 26 October.
Our honest take: wait a billing cycle or two before applying, unless you're already a Bandhan customer. Let the first wave of cardholders find the rough edges first.
If you do apply, treat the value-chart numbers as the absolute ceiling, work out your own realistic number from your actual spending, and compare that to what an established issuer would give you for the same fee.
If you want to see how a lifetime-free credit card compares before you commit to a fee, or want the full picture on how card fee waivers actually work in India, we've covered both in detail.
Bandhan also launched a FLASH digital card in GFF 2026. If you want the full picture, check our GFF 2026 roundup of credit card launches.
We've also covered the Scapia Axis Bank credit card launch, the RBL Bank Shoppers Stop cards and the AU Bank Ananta, Lakshya, Tejas and Prathama cards.
FAQs about Bandhan Bank's new credit cards
Which credit cards did Bandhan Bank launch in September 2026?
Bandhan Bank launched four Mastercard credit cards on 7 September 2026: Sparks, Ignite, Flare and Lumina. Joining fees run from nil on Sparks and Ignite to ₹9,999 + GST on Lumina, and each card has its own annual spend target for waiving the renewal fee.
Are the Bandhan Sparks and Ignite credit cards lifetime free?
No. Sparks renews at ₹499 + GST and Ignite at ₹999 + GST. The renewal fee is waived if you spend ₹50,000 (Sparks) or ₹1,00,000 (Ignite) in a year. If you want a card with no renewal fee at all, our lifetime-free credit card guide covers those options, and our fee waiver guide explains what to do when you miss a target.
Does Bandhan Bank charge different interest rates on the same card?
Yes, on Flare and Lumina. Flare charges 2.00% a month to existing Bandhan account holders and 3.50% to everyone else. Lumina charges 1.50% versus 3.50%. Sparks and Ignite charge 3.50% a month to all customers. This only costs you money if you carry a balance.
If you want to reduce your debt, our guide to consolidating credit card debt shows your options.
Which Bandhan Bank credit card has the lowest forex markup?
Lumina, at 1.00%. Flare charges 1.99%, while Sparks and Ignite charge 3.50%. Whichever card you use abroad, choose local currency when a terminal offers rupees, because paying in rupees can cost you more than the markup itself.
How many airport lounge visits do Bandhan's new credit cards give?
Lumina gives 8 domestic visits a quarter plus unlimited international visits. Flare gives 4 domestic and 1 international, Ignite gives 1 of each, and Sparks gives 1 domestic lounge access. Our credit card lounge access guide explains how access works in practice.
Should I trust the annual benefit numbers on Bandhan's Value Chart?
Treat them as a ceiling, not a promise. The Value Chart adds every possible perk into one annual figure, such as ₹10,000 a year for Sparks against a ₹499 fee and ₹1,78,900 for Lumina against ₹9,999. it’s better that you work out your own number from your actual spending, then compare it with what an established issuer gives for the same fee.
If you're weighing points against cashback, our reward points vs cashback guide can help you understand those better.
Should I apply for a Bandhan Bank credit card now?
If you already bank with Bandhan, Sparks or Ignite are reasonable low-commitment cards to add, and Flare and Lumina come with the lower interest rate. If you don't, wait a billing cycle or two. Nobody knows yet how smooth claims, redemptions or customer service are on cards this new.
Disclaimer
This is my honest read, not formal financial advice. I'm not your advisor, and before you act on anything big, run it past a professional. But here's exactly how I'd think about it.
About the Author
Abhijeet Kumar
Abhijeet loves to spend money (on books mostly) and does deep dive content about latest credit cards, hacks, and what changed in the credit card ecosystem recently. In his free time, he loves to read financial advice and lots of fiction.