How to Check Your CIBIL Score Free in India (2026): 6 Verified Ways, Ranked Honestly
Last updated on
Six genuinely free ways to check your CIBIL score in 2026 – cibil.com, your own bank's app, Paisabazaar, BankBazaar, CRED and KreditBee – plus what each one does with your number afterwards.
Too busy to read endless reviews & research?
Find the best cards that suit your lifestyle in 30 seconds
Try Monzy NowNo signup or email required
Checking your CIBIL score for free takes about three minutes, on any of the six legitimate routes – whether it’s cibil.com's official annual pull, your own bank's app, or an aggregator like Paisabazaar.
You verify your identity with an OTP, and your three-digit score appears on screen. None of it costs money, and none of it touches your score.
What differs is what each route offers afterwards. And that's worth knowing before you pick one.
TL;DR
- cibil.com gives you the official score with a full report, once a calendar year, for free.
- Your own bank's app – SBI's YONO, ICICI's iMobile and others – often shows it for free too, refreshed regularly.
- Paisabazaar, BankBazaar, CRED and KreditBee all refresh for free every month, pulled from CIBIL or Experian.
- None of the six touches your score – every one is a soft pull.
- The only real problem is the spam afterwards: subscription nudges, stream of sales calls, or loan-marketing funnel dressed up as a "free check."
If you're checking specifically to gauge whether a card application will go through, our guide on checking credit card eligibility without impacting your CIBIL score covers that fuller picture. We also have a guide on what a CIBIL score actually is.
Why most "free CIBIL score" sites aren't as free as they look
None of the six platforms below charge you money for the score, but a credit bureau pull costs someone something.
So, if you aren’t paying, the business model is usually one of three things:
- the platform sells you a paid monitoring plan once you're hooked (cibil.com's own move),
- it passes your mobile number to credit card and loan partners who then call and text you for months (Paisabazaar's actual business), or
- it uses the "free check" as the front door to a loan application funnel you never meant to enter (KreditBee's whole model).
None of this makes any of them unsafe to use. It just means "free" doesn't mean "no cost to you.” Pick the route whose cost you're actually willing to pay, and skip the sales screen that follows the score, whatever it's trying to sell you.
1. cibil.com – the official score, once a year
This is the one number that's genuinely your CIBIL score, straight from TransUnion CIBIL.
Go to cibil.com and choose the free score option. Fill in your name, PAN, date of birth and address, and verify the OTP sent to your phone. Then, answer a few security questions about accounts you've actually held, which CIBIL uses to confirm you're really you.
Takes 3 to 5 minutes, and your score and a summary report show up on screen at the end.
This free check resets on the calendar year (not 365 days from your last check). If you check it in December, your next free one is only weeks away.
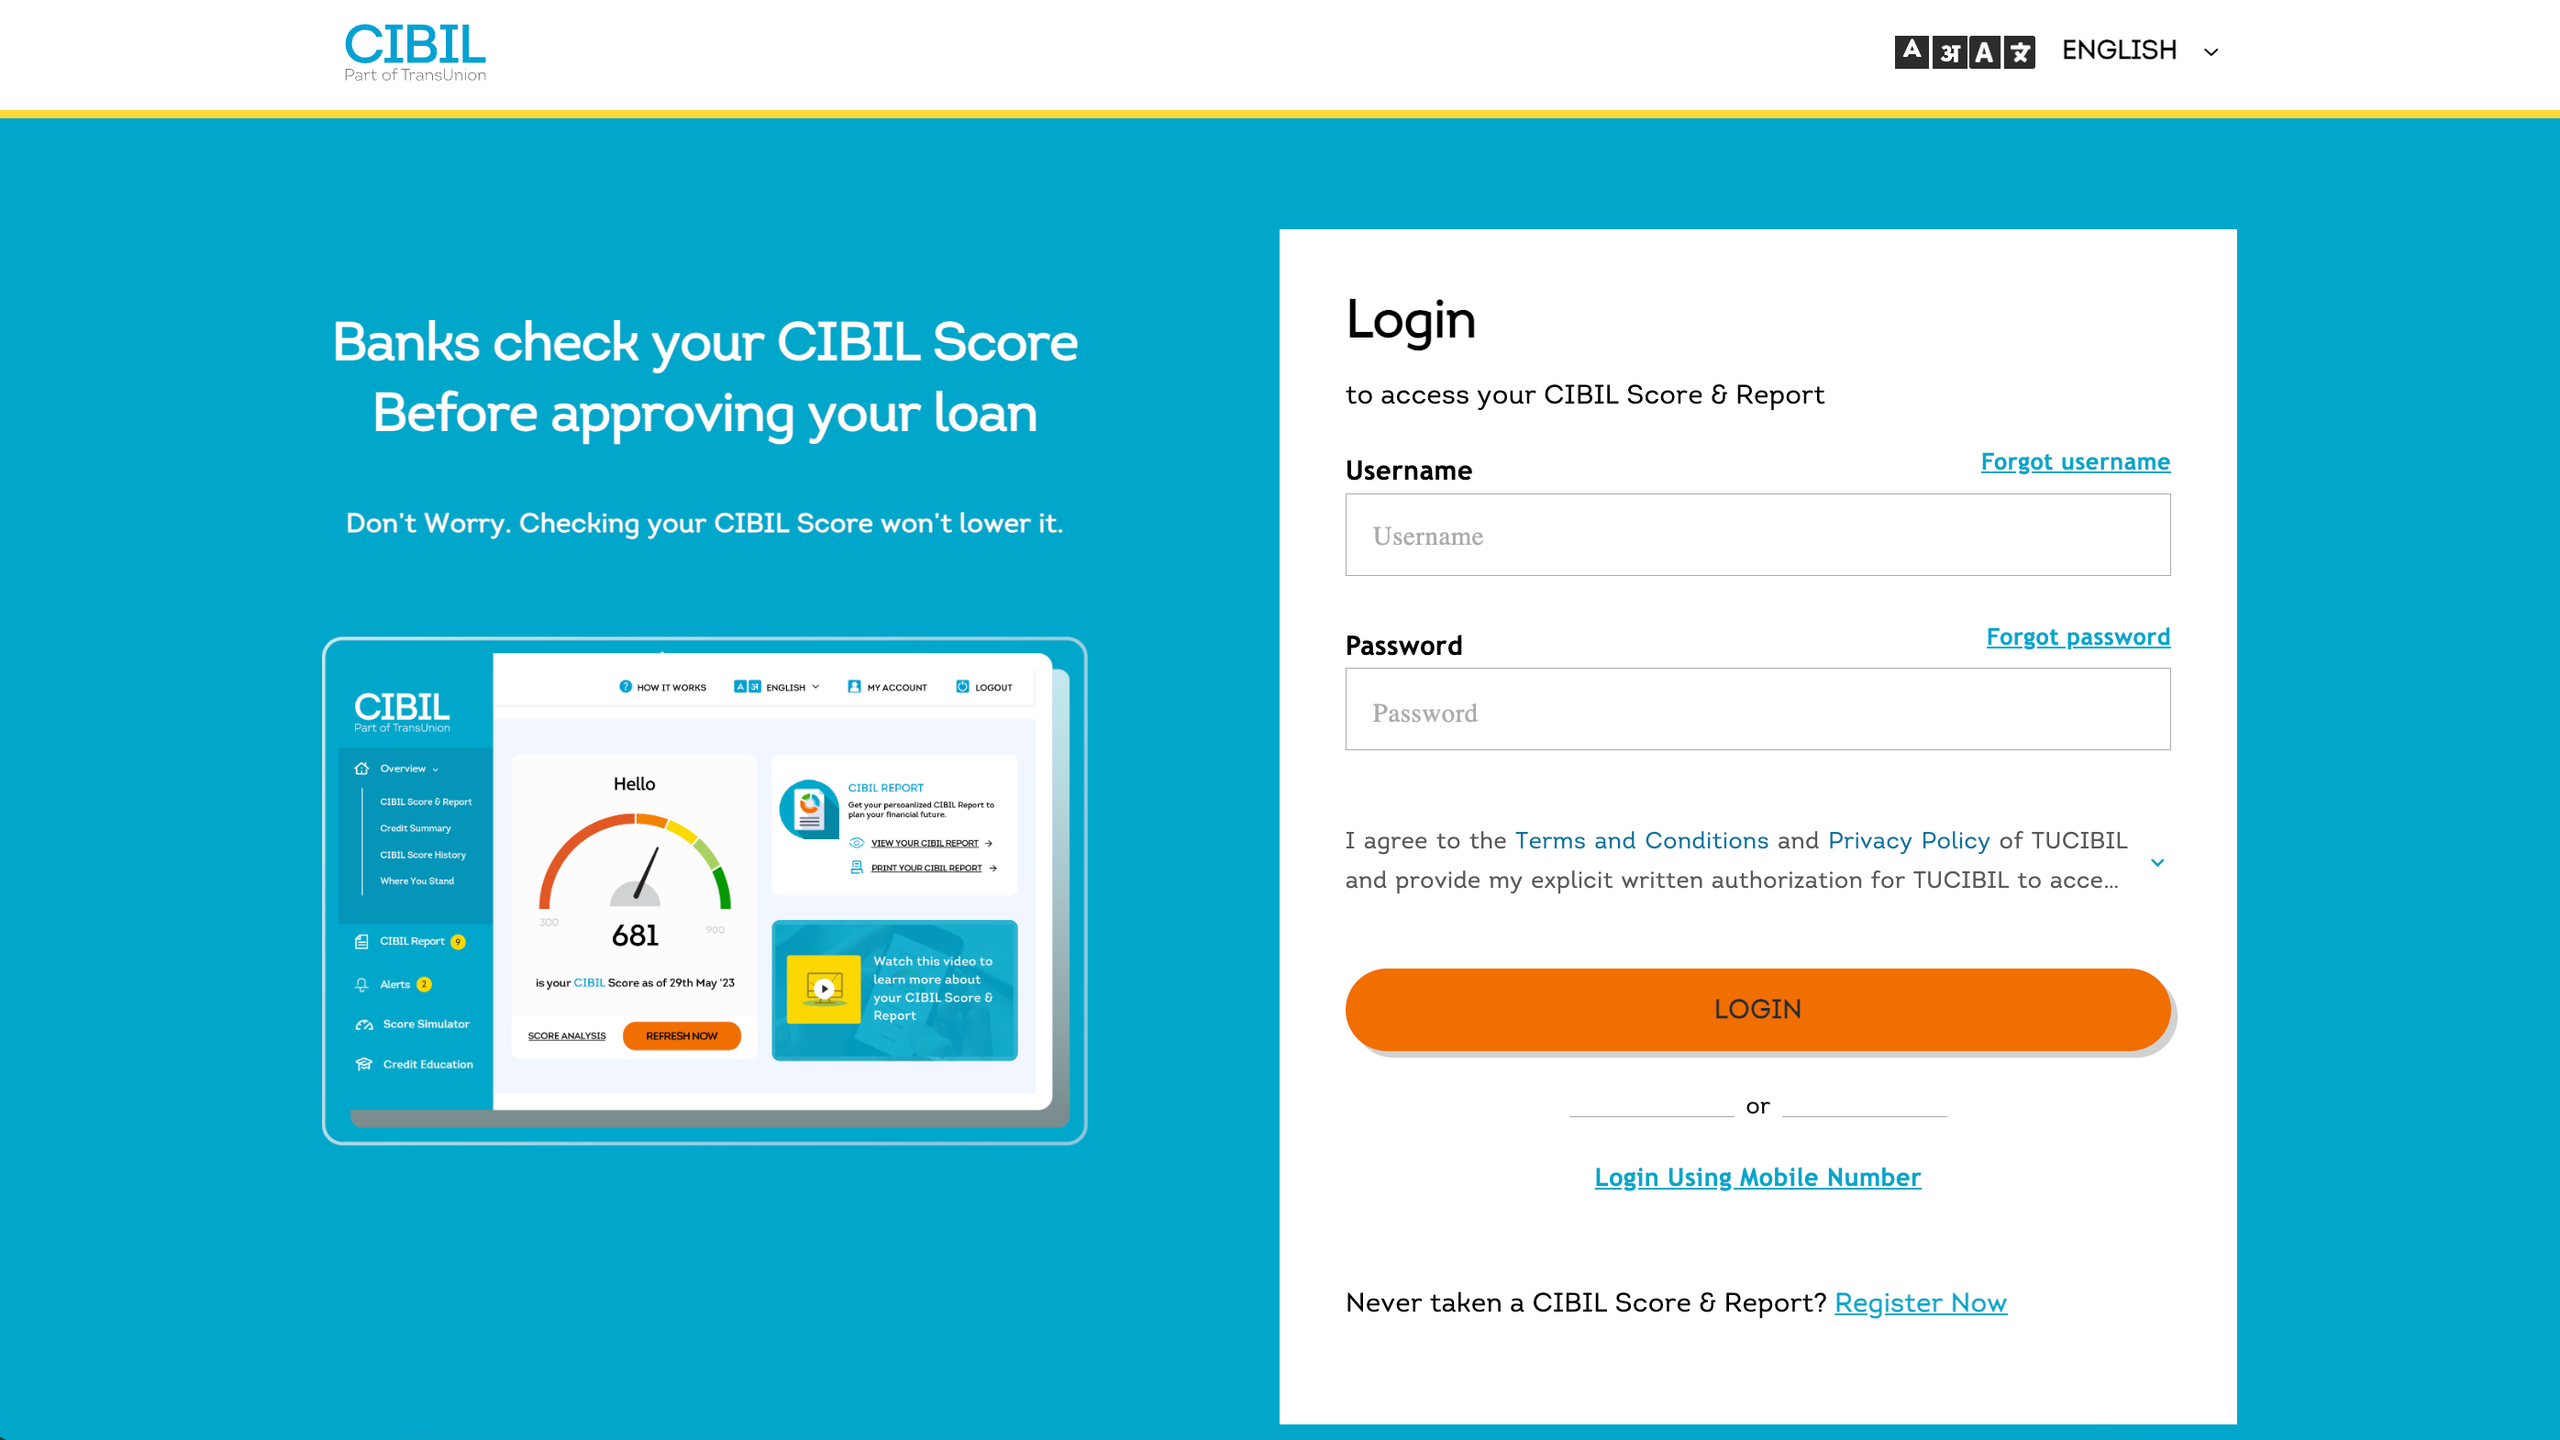
⚠️ Watch out: Right after your score loads, cibil.com also nudges you toward a paid subscription for ongoing monitoring. Skip it.
2. Your own bank's app – often free, and nobody new sees your data
A growing number of Indian banks now show your CIBIL score inside their own app, for customers who already hold an account.
SBI built this in directly – TransUnion CIBIL and SBI partnered to let YONO customers view and track their CIBIL score inside the app. It also offers a report breakdown and a score simulator.
ICICI Bank does something similar through iMobile Pay: log in, go to Accounts & Deposits, and open "My Credit Bureau Report" to view and download your CIBIL report.
Several other banks are adding versions of this feature to their own apps too.
You aren’t handing a fresh company your PAN and mobile number; the bank already has it, and checking your score doesn't create a new party in the loop.
⚠️ Watch out: this feature isn't universal, and banks have switched it on and off before – HDFC's own version has come and gone more than once over the years. Check your bank's app menu before assuming it's there. Don’t accidentally start a loan application, though. Pulling your score to apply for a loan is a different flow, and it can log as a hard enquiry on your credit report.
3. Paisabazaar – free, and it refreshes every month
Paisabazaar pulls your score from all four bureaus – CIBIL, Experian, Equifax and CRIF High Mark – and keeps refreshing it monthly without you asking again.
Enter your mobile number, verify the OTP, and your account is created on the spot – no name, PAN or other thousand details needed just to see the score. From then on, your score updates automatically every month, and you can log back in any time to see it.
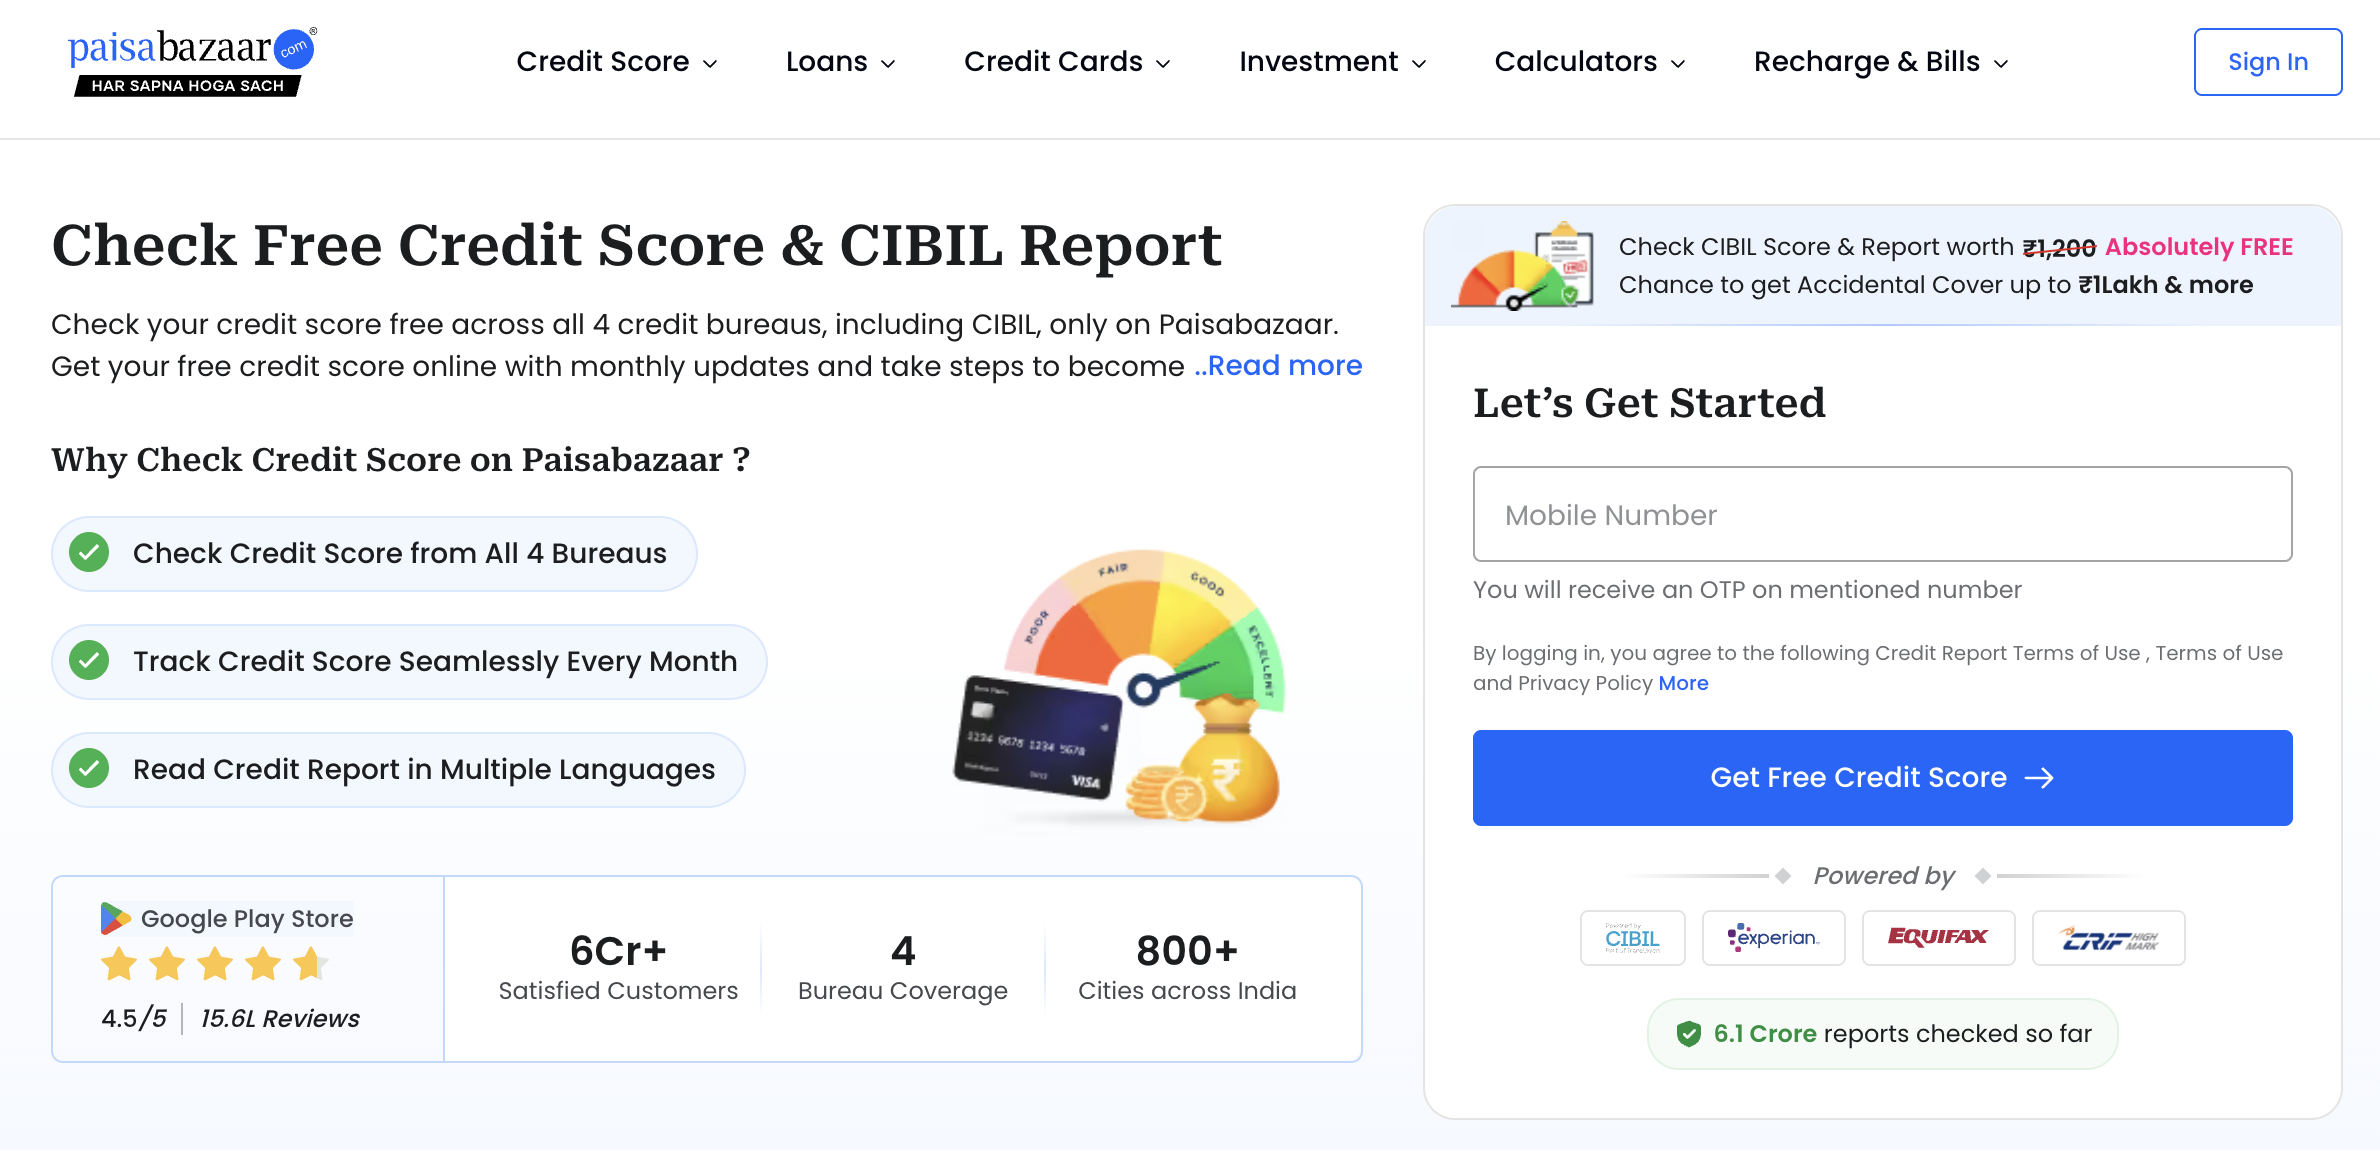
⚠️ Watch out: Expect calls and SMS about credit cards and loans afterward. The score itself, though, stays free indefinitely.
4. BankBazaar – free, but Experian score, not CIBIL
BankBazaar's free check pulls from Experian, not TransUnion CIBIL. The two bureaus track largely the same data and your numbers are usually close, but they aren't always identical. So, don't be surprised if this figure sits a few points off whatever cibil.com showed you.
Enter your name, mobile number and email, verify the OTP, confirm your age, and your score appears in under a minute.
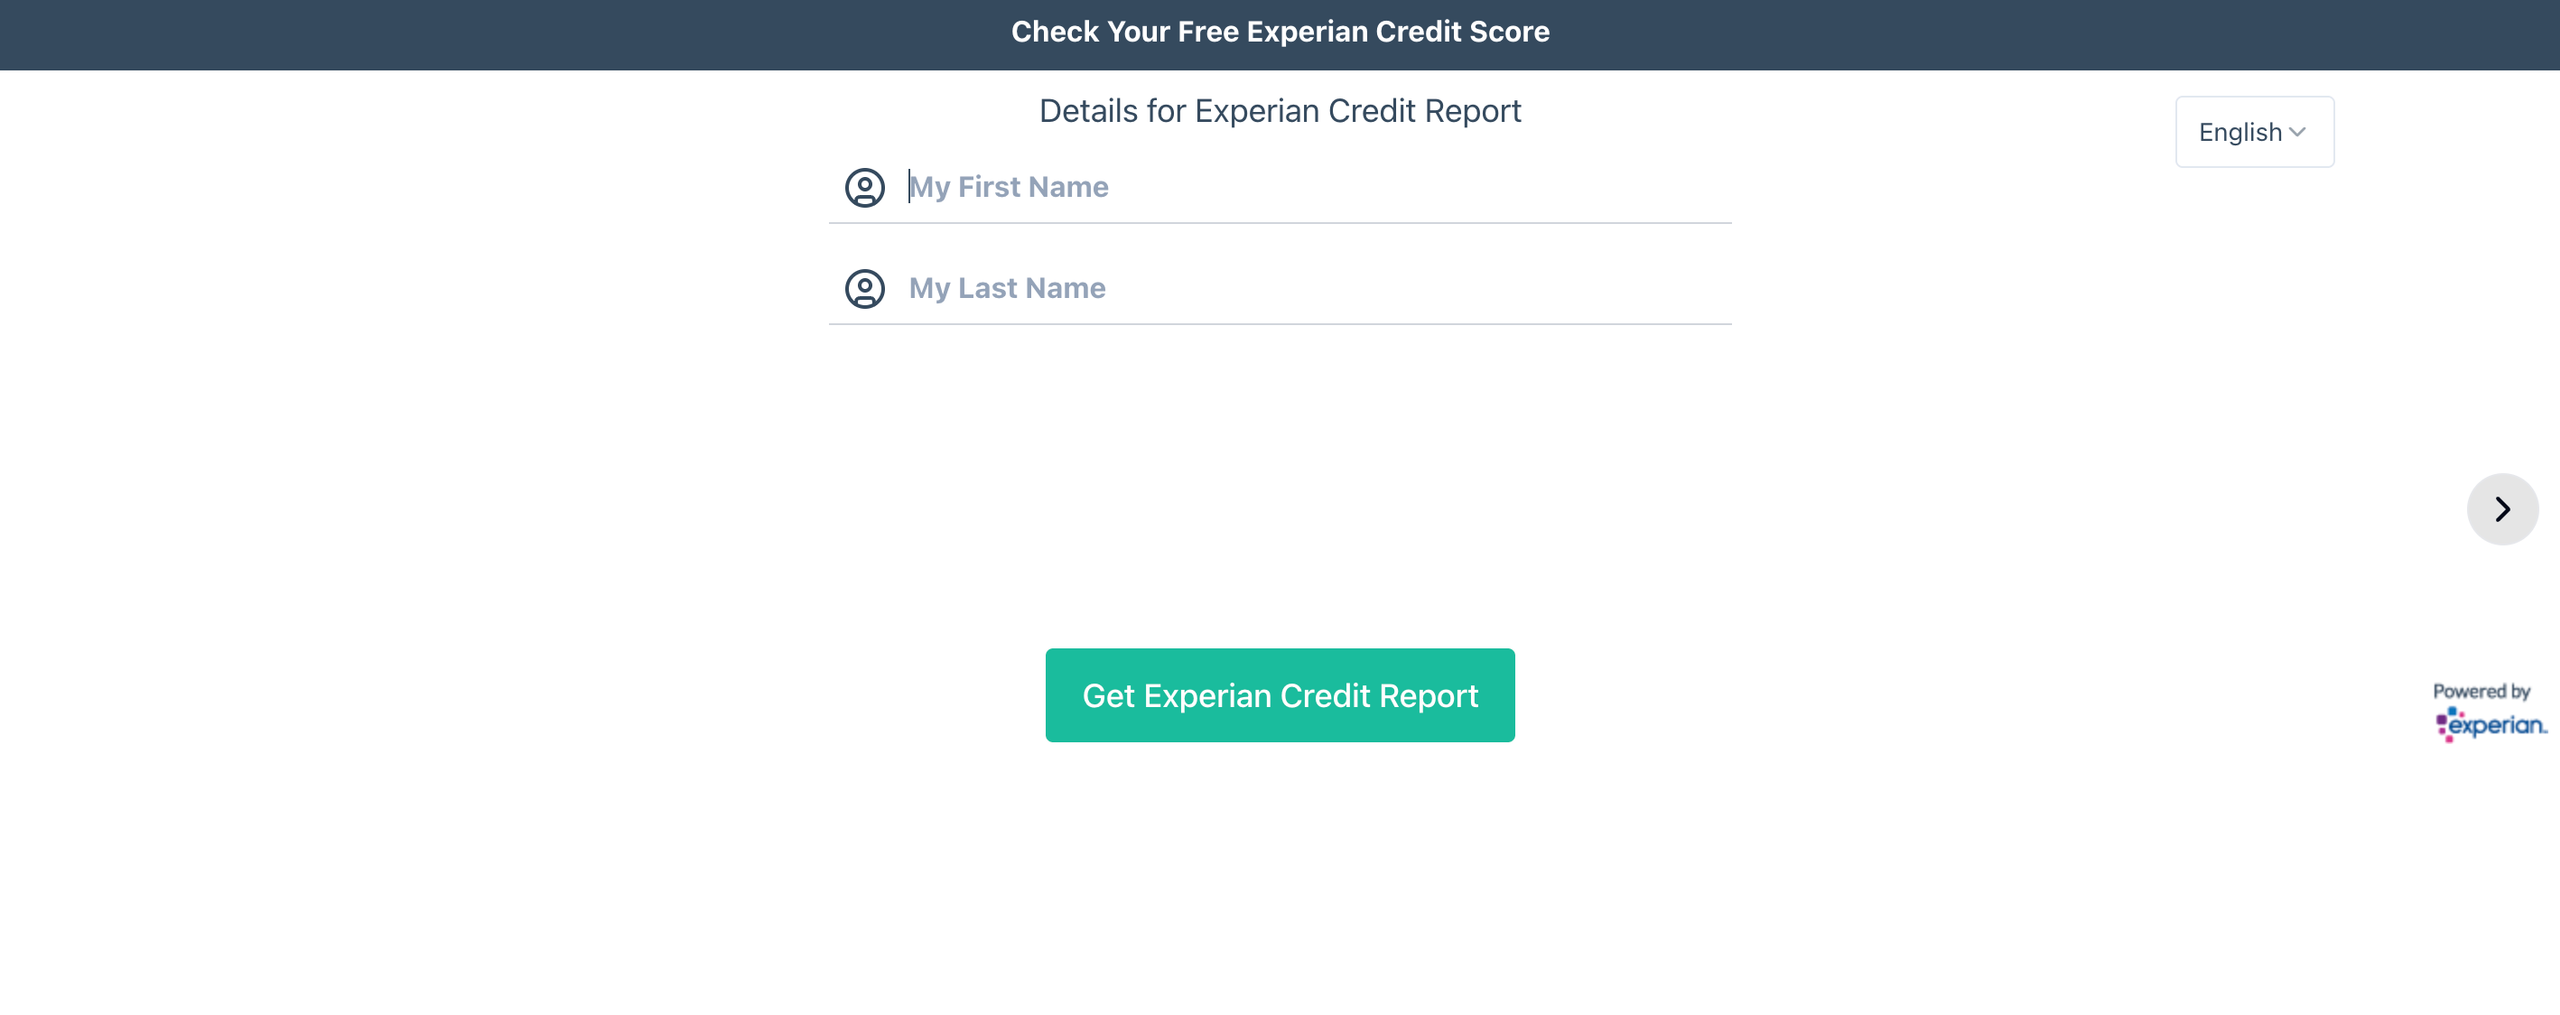
⚠️ Watch out: If this score looks lower than one from another platform, check the bureau before you panic – a 740 from Experian and a 752 from CIBIL are both fine; each bureau has a different way of measurement.
5. CRED – free, but only if you're already on it
CRED shows your CIBIL score for free inside the app, refreshed monthly, if you're already a CRED user. You'll need to have signed up already, which means you had a credit card added during the onboarding process.
Open the app, go to the credit score section, and it pulls your score without the need for any extra signup or verification.
⚠️ Watch out: Don't join CRED purely to check your score once. Any other option here gets you the same number without the onboarding.
6. KreditBee – free, but read what you're signing up for
KreditBee's check works like the others – mobile number linked to your PAN, OTP, a few KYC details, and your report generates in minutes. Getting the score itself costs nothing.
⚠️ Watch out: KreditBee's actual business is instant personal loans, not credit monitoring. Completing full KYC here plugs you into their loan marketing, so expect pre-approved loan offers – the real "free, until it isn't" trap, minus any actual subscription charge.
All six, side by side
Platform | Bureau | Refresh | What you hand over | The catch |
|---|---|---|---|---|
cibil.com | CIBIL (official) | Once a calendar year | Full KYC | Nudges a paid subscription after |
Your bank's app | CIBIL (via partner banks) | Varies by bank | Nothing new — you're already a customer | Not every bank offers it, and it can be pulled without notice |
Paisabazaar | CIBIL + 3 others | Monthly | Mobile number | Card/loan calls afterward |
BankBazaar | Experian only | On demand | Name, mobile, email | Not the same number as CIBIL |
CRED | CIBIL | Monthly | Nothing new — you're already in | Not worth joining just for this |
KreditBee | CIBIL | On demand | Full KYC | Feeds you into loan offers |
Checking your own score never hurts it – here's why
Checking your own score through any of these six is a soft pull: a check that never leaves a mark. You can check it every day for a year, and your score won't move a point because of it.
What does cost you a few points is a hard pull of your credit report — the check a lender runs the moment you actually apply for a card or loan. That knocks off 5 to 10 points and stays visible to other lenders for 24 months. If you want the exact point swing, our CIBIL impact calculator breakdown does that math.
None of these six methods are loan or card applications, so none of them dents your score. If you want the full breakdown of which everyday actions fall into which category, we've mapped all ten of them out separately.
How often should you actually check it
Monthly is genuinely fine. Weekly is pointless, not risky – just pointless.
Since 1 January 2025, RBI rules require lenders to report your account activity to the bureaus every 15 days, so checking twice inside that window shows no change as such.
The one time to check outside your usual schedule is right after you've paid down a balance or closed an account. It’s so you can confirm it reported the way you expected. Give it the full 15 days first to update the bureau.
If you want your first unsecured card, apply where your salary account already sits. If you need to build your score up first, start with an FD-backed card – IDFC FIRST Classic or SBI Unnati are both reasonable starting points.
So which one should you actually use
If you want the real, official number once a year: cibil.com. Check your own bank's app first, though — if it has the feature, it's the cleanest route on this list, since nobody new gets your details.
For everything in between, use Paisabazaar. It's free indefinitely, pulls all four bureaus, and refreshes on its own every month without you doing anything.
Skip CRED unless you're already using it for your card bills, and go into KreditBee knowing you're opening the door to loan offers, not just a score.
If the number's lower than you'd like, our CIBIL improvement guide has the 90-day and 12-month plans for improving it. If you need it up fast specifically, our 90-day fast plan covers just the utilisation and dispute levers.
And if something on your report looks wrong once you've checked it, here's how to dispute an error on your CIBIL report.
FAQs about checking CIBIL score for free
Is it actually free to check my CIBIL score, or is there a catch?
The score itself is genuinely free on every platform in this list. None of them charge you just to see the number. The "catch," where one exists, is what comes after: a subscription nudge on cibil.com, marketing calls from lead-gen sites, or loan offers from lending apps.
Can I check my CIBIL score online without visiting a branch?
Yes, all six routes here are entirely online. None of them need a branch visit, a phone call, or a physical form – just your phone for the OTP.
Can I check my CIBIL score using only my PAN card?
Your PAN identifies your file, but no platform hands you a score from a PAN number alone – you'll always also verify with an OTP to your registered mobile number.
Does checking my own CIBIL score lower it?
No. Checking your own score, on any of these five platforms, however often you do it, is a soft pull with zero effect on your number. Only a hard pull, logged when you actually apply for a card or loan, costs you points.
Is there a way to check my CIBIL score without affecting it at all?
Yes. CIBIL’s report, your own bank's app credit score, and the score provided by Paisabazaar, BankBazaar, etc, are a soft pull by default. The only thing that puts points at risk is starting an actual credit application, including the "apply now" flow some bank apps place right next to their score dashboard. Check the score, skip the application button, and your number doesn't move.
How often should I check my CIBIL score?
Monthly is enough for almost everyone. Your file only updates every 15 days under current RBI rules, so checking more often than that shows stale numbers.
Do I need to pay to see my full CIBIL report, or just the score?
The three-digit score is free everywhere on this list, and cibil.com's basic free report is included in your one annual check. What's paid is the ongoing subscription for monthly official reports – skip it, since Paisabazaar gives you that refresh for free anyway.
Does my own bank show my CIBIL score for free?
Some do. SBI's YONO app and ICICI's iMobile Pay both show it to existing customers at no cost, and other banks are adding similar features. It isn't universal yet, so check your own bank's app menu – usually under Loans or a "Credit Score" tile – before assuming it's missing.
Why does my score look different on BankBazaar than on cibil.com?
BankBazaar pulls from Experian, not TransUnion CIBIL. The two bureaus track largely the same data, but their numbers aren't always identical. So, a 740 from Experian and a 752 from CIBIL are both fine, since each bureau measures a little differently.
Do I need to check my score on all six platforms, or is one enough?
One is enough for most people. Use cibil.com once a year for the official number, your bank's app if it offers the feature, and Paisabazaar for everything in between. It's free indefinitely, pulls all four bureaus, and refreshes on its own every month.
Is the score CRED shows me the real CIBIL score, or an estimate?
It's the real one. CRED pulls your genuine CIBIL score, refreshed monthly, the same as cibil.com. It’s just that CRED works only if you're already a user, unlike the other four options on this list.
Monzy's take
Start with your own bank's app before anywhere else. It's the one route where checking your score doesn't introduce you to a new company at all.
If it isn't there, cibil.com once a year and Paisabazaar in between covers you completely, for free, indefinitely. Everything past that is optional, and most of it is a company hoping the free score is enough to keep you around for something that isn't.
Disclaimer
This is my honest read, not formal financial advice. I'm not your advisor, and before you act on anything big, run it past a professional. But here's exactly how I'd think about it.
About the Author
Abhijeet Kumar
Abhijeet loves to spend money (on books mostly) and does deep dive content about latest credit cards, hacks, and what changed in the credit card ecosystem recently. In his free time, he loves to read financial advice and lots of fiction.